 Remittance companies
 Crypto OTC desks
 Bitcoin ATM operators
 ATM operators
 Small businesses
Starting a money transfer business in Canada
The short answer
To start a money transfer business in Canada, first set up your company. Appoint a compliance officer and write your anti-money laundering program. Then register with FINTRAC as a money services business before you take a single payment. Check whether the RPAA applies to you too, and line up payment rails for your customers' money.
Opening a remittance business
3 of 6- 1Company set upDone
- 2Compliance officer namedDone
- 3AML program writtenDone
- 4FINTRAC registrationIn review
- 5RPAA checkTo do
- 6Payment railsTo do
On this page
- Is a money transfer business an MSB?
- How to start an MSB in Canada, step by step
- Which MSB services will you register for?
- Start with your flow of funds
- Do you need to register under the RPAA too?
- How much does it cost to start an MSB in Canada?
- How long does it take to start an MSB?
- Where will your MSB's money go?
- Your first-year compliance calendar
- Sources
Is a money transfer business an MSB?
Yes. To start a money transfer business in Canada, you start a money services business (MSB). Under federal law, remitting or transmitting funds is an MSB service, like foreign exchange dealing and dealing in virtual currency.
That brings duties from day one. You run an anti-money laundering compliance program, verify clients, keep records and report to FINTRAC. This guide is the order to do things in. Our other guides hold the detail for each step.
The last step is a home for your customers' money. Registered MSBs can apply to us for payment rails for money service businesses. You collect by Interac e-Transfer and settle by EFT or wire, from one wallet.
How to start an MSB in Canada, step by step
- Map how money will move
Write down where your customers' money comes from, where it waits and where it goes. FINTRAC asks for your expected yearly amount for each service, and payment providers ask for the same picture.
- Set up your business
Incorporate, or set up a partnership or sole proprietorship. FINTRAC asks for your incorporation records and a document that shows your ownership, control and structure.
- Check who can own and run it
FINTRAC won't register a business if its chief executive, president, a director or a 20% owner is ineligible. Each of them needs a criminal record check.
- Build your compliance program
Appoint a compliance officer, write your policies, assess your risks and plan your training. Our FINTRAC compliance program guide covers each part.
- Register with FINTRAC
Send the pre-registration request, then a complete application. You must be registered before you start operating. Our FINTRAC MSB registration guide has every step.
- Check whether the RPAA applies
If you hold customers' funds or start electronic transfers for them, you may also need Bank of Canada registration. Our RPAA registration guide explains the tests.
- Check your province
Your province may have rules of its own for money services businesses. Check them, and register with FINTRAC either way.
- Set up your payment rails
Choose where your customers' money will land and how it reaches your liquidity and payout partners. Start early: providers ask for your FINTRAC registration and your compliance program first.
Which MSB services will you register for?
FINTRAC registers your business for the MSB services it offers. Match your business plan to those services before you fill in the form. Many businesses offer more than one.
| If your business plan is | You register for |
|---|---|
| Sending customers' money to family or suppliers abroad | Remitting or transmitting funds |
| Buying and selling foreign currency, at a counter or online | Foreign exchange dealing |
| A crypto exchange, an OTC desk or a Bitcoin ATM | Dealing in virtual currency |
| Paying invoices for clients, or holding funds between a buyer and a seller | Possibly remitting or transmitting funds: check with FINTRAC |
| Cashing cheques for customers | Cheque cashing |
| Running a crowdfunding platform | Crowdfunding platform services |
Add a service later, and you tell FINTRAC within 30 days. Payment providers read the services on your entry too, so register for everything you plan to do.
Start with your flow of funds
A flow of funds is the path money takes through your business. For a remittance company, it often looks like this.
- Customers pay you in Canada
They pay by Interac e-Transfer, often by answering an e-Transfer request you send them.
- You collect the day's payments
Every payment lands in one wallet as it arrives, so you can match it to the transfer it pays for.
- You settle with your liquidity provider
You send the day's total in Canadian dollars by EFT or same-day wire.
- Your partners convert and pay out
Your liquidity provider converts the funds, and your payout partner delivers them to each recipient abroad.
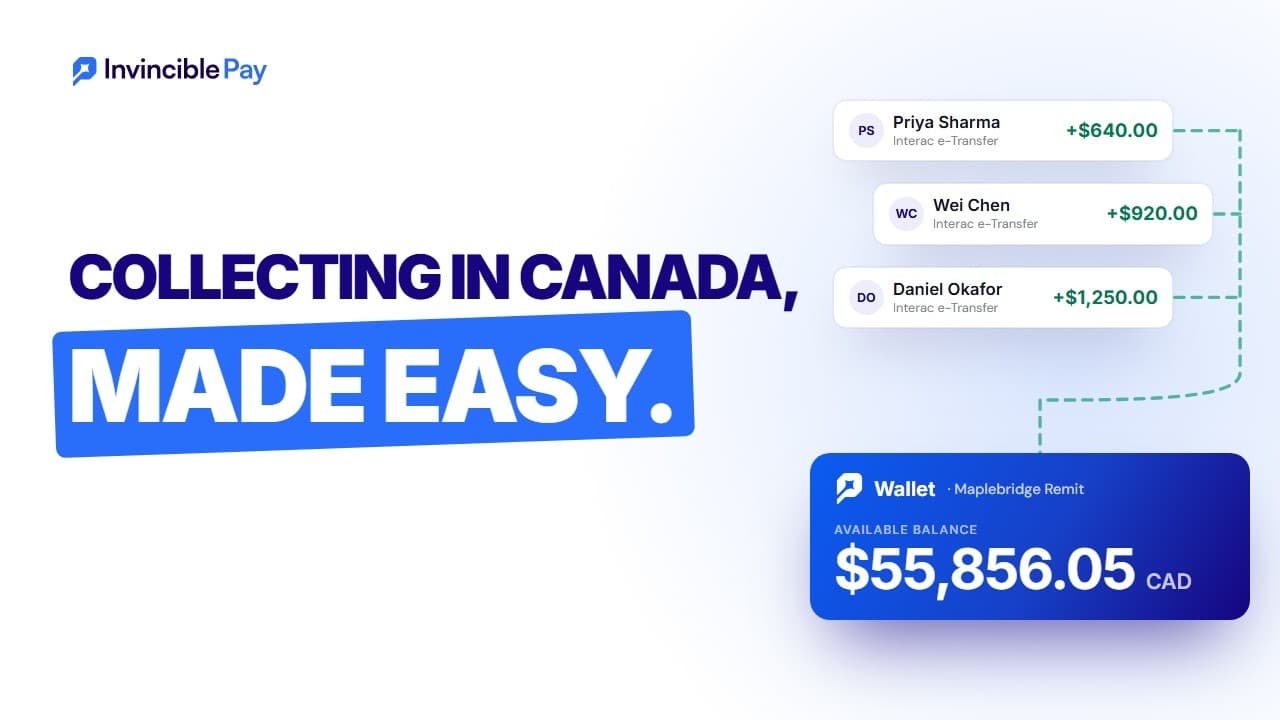
The video walks through this flow for a remittance company. Our remittance payments page has the transcript.
Write yours down early. Your risk assessment depends on it, and payment providers ask for it before they onboard you.
We work only in Canadian dollars and don't convert currency. In the flow above, we handle the first three steps. The fourth stays with your partners.
Do you need to register under the RPAA too?
Possibly. The Retail Payment Activities Act (RPAA) covers payment service providers. These are businesses that perform payment functions, such as holding funds for users or starting electronic transfers at their request.
If it applies to you, register with the Bank of Canada before you perform those activities. The application fee is $2,500, and it's non-refundable. Our RPAA registration guide walks through the four tests.
The two registrations look at different things. FINTRAC looks at anti-money laundering. The Bank of Canada looks at operational risk and how you safeguard users' funds. Its application asks about your FINTRAC registration.
Invincible Pay holds both. We're registered with FINTRAC as a money services business (C100000702) and with the Bank of Canada as a payment service provider under the Retail Payment Activities Act.
How much does it cost to start an MSB in Canada?
FINTRAC charges nothing to register. Most of the cost of starting an MSB comes from compliance work and payment rails.
| Cost | Amount | What it covers |
|---|---|---|
| FINTRAC registration | No fee | Free, but send a complete application: FINTRAC closes incomplete ones and asks for a complete one. |
| Bank of Canada registration | $2,500 | Only if the RPAA applies to you. One time and non-refundable. Registered PSPs also pay an annual assessment fee. |
| Criminal record checks | Varies | One for each leader and each owner of 20% or more, plus certified translations where needed. |
| Compliance help | Varies | A consultant to write your program or run your effectiveness review, if you use one. |
| Payment rails with us | $500 setup | Then a $500 monthly minimum that counts toward your fees of $1.95 + 0.20% per transaction. |
Other payment providers typically charge $3,000 or more to onboard an MSB and $1,500 or more a month. For wires and our crypto on- and off-ramp, reach out for pricing.
How long does it take to start an MSB?
FINTRAC processes most complete registration applications within 3 months. Complex ones can take longer, and you can't operate until you're registered.
The Bank of Canada doesn't publish a fixed timeline for RPAA registration. It starts its review once the fee is paid, and the Department of Finance screens each application for national security.
Payment rails can be quick once you're registered. With us, you apply in about 20 minutes and usually get a decision within 3 business days. You can process payments within 5, once we have your documents.
Where will your MSB's money go?
For many new MSBs, this is the hardest step. Banks are wary of MSBs, and most payment platforms' terms exclude money services businesses.
FINTRAC's registration form asks for your bank account information, so start those conversations early.
For collecting from customers and paying out, we give registered MSBs a payment wallet. Send up to $25,000 per transfer, with no daily limit. Your liquidity provider is paid from the same wallet, by EFT or same-day wire.
Have these ready when you talk to us
- Your FINTRAC registration number, and the services on your entry
- The compliance program from step 4, including how you'll onboard customers and watch their transactions
- The company records from step 2. Directors, officers and anyone who owns 25% or more verify their identity online
- The flow of funds you mapped in step 1: where customer money comes from and where it goes next
- A compliance contact, often your compliance officer, who can answer our questions within 24 hours
Your first customer payments
Send each customer an e-Transfer request for the transfer they've booked. They accept it in their banking app, and the money lands in your wallet, ready to match to the transfer.
Your first-year compliance calendar
Once you're operating, these deadlines come round again. Put them in your calendar from day one.
| When | What you do |
|---|---|
| Within 30 days of a change | Tell FINTRAC about new agents, locations, activities or contacts. |
| Within 30 days of a FINTRAC question | Answer its clarification request. An unanswered one can lead to revocation. |
| As each report falls due | File suspicious transaction, large cash and electronic funds transfer reports on time. |
| All year | Train staff and agents, and keep your risk assessment current. |
| At least every 2 years | Run your effectiveness review, then report it to a senior officer within 30 days. |
| Before your expiry date | Renew your FINTRAC registration. It lasts 2 years. |
Sources
We checked every rule in this guide against these official pages on October 23, 2026. Rules change, so read the current version before you file anything. This guide explains what the rules say. It isn't legal advice.
- Money services businesses (MSBs)FINTRAC
- Register your money services business or your foreign money services businessFINTRAC
- Check to see if you need to register with FINTRAC as a money services businessFINTRAC
- Crowdfunding platforms and certain payment service providers must register with FINTRACFINTRAC
- Who is not eligible to register as a money services business or act as an agent or mandataryFINTRAC
- Clarification requests, updates, renewals and cessations of an MSB registrationFINTRAC
- Compliance program requirementsFINTRAC
- Criteria for registering payment service providersBank of Canada
- Supervisory framework: registrationBank of Canada
- Frequently asked questions about retail payments supervisionBank of Canada
- Proceeds of Crime (Money Laundering) and Terrorist Financing ActJustice Laws Website
- Retail Payment Activities ActJustice Laws Website